
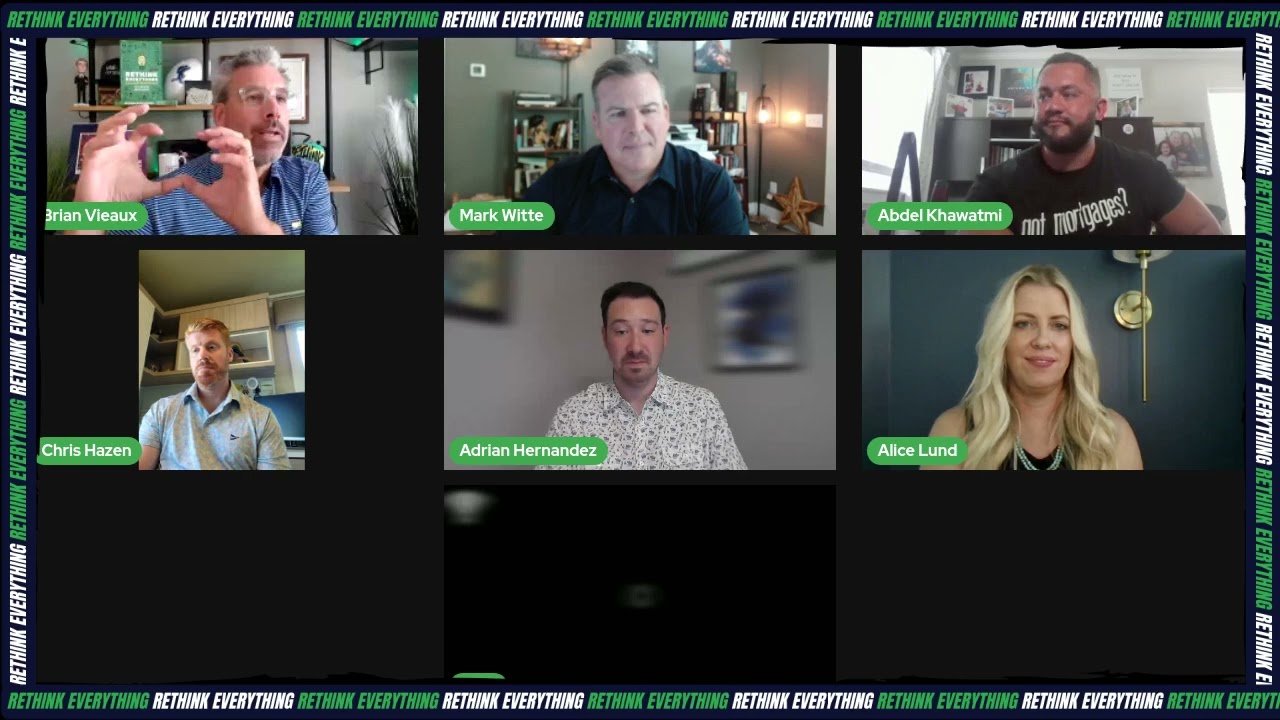
In a mortgage market that demands early intervention and consistent value, top-performing loan officers are shifting away from transactional 'apply now' calls to action. Brian Vieaux, President and COO of FinLocker, recently hosted a panel with Alice Lund (LeaderOne Financial), Abdel Khawatmi (PRMG), Mark Witte (Highland Mortgage), and Minh Nguyen (What’s a Mortgage) to discuss the real-world impact of white-labeled consumer engagement apps. By utilizing branded versions of the FinLocker platform—such as 'Manifest With Us,' 'Path Home,' and 'Wham Wallet'—these professionals are bridging the gap between social media engagement and mortgage readiness. This episode explores how education-first strategies, co-branded realtor partnerships, and automated credit monitoring are reshaping the consumer journey from the top of the funnel to post-closing equity tracking.
Conversation originally published August 5, 2024. Recap added October 24, 2026.
Watch the original conversation on YouTube.
The Shift to Holistic Financial Health and Manifestation
Alice Lund of LeaderOne Financial introduced their branded app, 'Manifest With Us,' which emphasizes a spiritual and holistic approach to financial wellness. The goal is to insulate clients who are not ready to buy today, moving beyond the industry's traditional habit of simply placing unqualified leads into a static CRM bucket or manual follow-up file. By leading with wellness, Lund aims to talk to consumers when they first realize they want a home, rather than waiting for the day they are ready to apply.
Lund highlighted that the app serves as a 'tangible path' for consumers who might otherwise feel they are floating in uncertainty. Instead of a simple denial, users engage with score simulators and tools that show exactly what happens if they pay their bills on time for several months. This process helps consumers believe homeownership is possible by providing a visual roadmap for their financial future, which keeps them engaged with the loan officer throughout the long-term preparation phase.
The 'Manifest With Us' approach also bridges the gap between loan officers and real estate partners. Lund noted that Realtors have been highly receptive to the tool because it acts as a value-add for their own clients. By providing a branded education platform, the loan officer 'locks arms' with the Realtor to ensure the consumer is well-prepared. This collaborative education strategy moves away from the 'sausage and cheese' social events toward meaningful, tech-driven community service that builds lasting professional authority.
Driving Leads Through the 'Wham Wallet' and Social Media
Minh Nguyen, known for his 'What’s a Mortgage' brand, discussed the 'Wham Wallet' as a tool for creating 'sticky' consumer relationships. Nguyen leverages his massive social following by offering high-value features like value checks, which tell consumers if a home is overpriced before they write an offer. This 'fear factor' of overpaying drives app downloads and creates a captive audience. By using the wallet as glue, Nguyen ensures that he remains the central figure in the consumer's financial journey.
Nguyen’s strategy focuses on 'layering' content to build trust over time. He consistently provides community-service content—such as how to use a 401k for a down payment or reading a credit report—without asking for immediate value in return. This approach avoids coming across as 'thirsty' for a loan. By the time he suggests a tool like the Wham Wallet, the consumer trust is already established, making them more willing to share sensitive information like a Social Security number when they are ready to move forward.
The Wham Wallet also serves as a critical resource in a post-NAR settlement environment. Nguyen noted that the app allows users to search for homes and see what agents see without immediately committing to a buyer’s agency contract. This makes it a perfect tool for DIY-minded consumers who want to explore the market privately. By providing these search tools and refinance simulators, Nguyen positions the app as a virtual loan officer that handles the early-stage inquiries and keeps the consumer within his branded ecosystem.
Co-Branding and Realtor Partnership Strategies
Mark Witte of Highland Mortgage shared how his team uses 'Ready, Set, Home' to facilitate earlier conversations with real estate partners. By providing realtors with their own unique URLs, the app becomes a value-added service the agent can offer to their database. This strategy keeps the loan officer front-and-center in the consumer's palm. Witte emphasized that this co-branding creates a seamless experience where the Realtor is visible on the landing page, reinforcing the partnership from the very first click.
The panel discussed how this technology acts as a CRM for realtors who may not have robust systems of their own. It allows the loan officer and the realtor to collaborate in the education process rather than just passing leads back and forth. Witte noted that this arms-length engagement is often more comfortable for consumers who are self-conscious about their finances. The app allows them to explore their mortgage readiness privately, using the platform as a safe space to run scenarios before they are ready for a direct conversation.
Witte highlighted the success of co-branded presentations and neighborhood outreach. By using a PowerPoint specifically tailored to 'Ready, Set, Home,' his team has been able to capture the attention of multiple Realtors at once. One loan officer in Alabama reportedly signed up over 100 consumers in her first two weeks by marketing the app to local hero groups like teachers and fire departments. This demonstrates how a branded app can serve as a powerful entry point for new community relationships and direct-to-consumer marketing.
Operational Efficiency: Alerts and Credit Cost Management
Abdel Khawatmi of PRMG emphasized that 'Path Home' has become an essential tool for staying top-of-mind while managing overhead. With the rising cost of credit reports, the app’s ability to perform soft pulls and provide credit monitoring is a massive operational win. It prevents 'trigger lead' calls from competitors that typically occur when a hard credit pull is executed. This allows the loan officer to advise the client on their credit journey without exposing them to predatory marketing from other lenders.
Khawatmi also detailed the importance of automated alerts provided by the FinLocker platform. When a consumer’s credit score improves or they reach a mortgage readiness milestone, the loan officer receives a notification. This allows for a timely, supportive phone call to congratulate the client, reinforcing the relationship and moving the lead closer to a formal application. These alerts help the loan officer know exactly when to reach out, making the communication more relevant and less intrusive for the consumer.
The impact of this technology at PRMG has been significant. Khawatmi noted that loan officers using the app saw a 279% increase in their business metrics compared to those who did not. By integrating 'Path Home' from the initial touch to post-closing equity tracking, the team can ensure the client never gets 'veered' in different directions by outside media or other financial apps. The goal is to keep the consumer focused on their homeownership goals within a single, secure, and branded environment.
Advanced CRM Integrations and Lead Magnets
Brian Vieaux highlighted that the FinLocker ecosystem is designed to amplify the loan officer’s local brand through deep CRM integrations. A key component of this is the integration with platforms like Total Expert. When a new user signs up for a branded app through a social media link or a QR code, a new lead record is automatically created in the loan officer’s CRM instance. This automation ensures that no lead is lost and allows for immediate follow-up through customized marketing journeys.
A recent success story involved Jordan Nutter of NFM Lending, who generated 249 new downloads from a single video about budgeting. Remarkably, 72% of those were net-new leads, and approximately 14% indicated they were ready to move forward immediately. This demonstrates the power of using a 'home stretch' style app as a lead magnet that filters for readiness in real-time. Instead of a generic 'apply now' button, the app provides a valuable tool that captures consumer data while providing them with an immediate benefit.
The integration also extends to the communication phase. Total Expert helps power the journeys that kick off when credit score changes occur within the app. This means the technology is working in the background to send relevant updates to the consumer, while also alerting the loan officer to the change. By combining the data-rich environment of FinLocker with the marketing automation of a CRM, loan officers can manage thousands of potential leads with the same level of personalization as a small referral file.
The Digital Business Card and Future Product Updates
Brian Vieaux introduced the upcoming 'digital business card' feature, designed to help loan officers invite consumers to their app with ease. This mobile-stored card will allow a professional to share their unique link instantly, providing the consumer with the app's value proposition and the loan officer's contact information. This is part of a larger push to ensure the loan officer remains the central figure in the financial education process, providing a modern alternative to traditional paper marketing materials.
The platform is also expanding to include 'Keysteps,' a version of the product for loan officers whose companies do not yet have an enterprise agreement. This allows individual professionals to leverage the same mortgage readiness tools and credit monitoring features independently. Vieaux emphasized that the local loan officer is the single best resource for financial education, and the platform’s goal is to provide the tools necessary to scale that expertise to a wider audience of prospective homebuyers.
Further updates to the mortgage readiness widget are also underway. The widget, often referred to as a home ownership snapshot, has become the primary entry point for new users. Data shows that consumers are using it as a dynamic calculator, running multiple scenarios to find their optimal loan approvability. FinLocker is continuing to iterate on this feature to provide even more granular tools for consumers to understand their financial standing and the steps needed to reach their homeownership goals.
Looking Toward 2025: Refinance Readiness and Outreach
As the market anticipates potential rate shifts, the panel is shifting its focus toward 'Refi Ready' features. Minh Nguyen is developing refinance webinars to help homeowners determine their breakeven point using the app's simulator. By teaching consumers 'why to wait' rather than just refinancing for the sake of a transaction, he builds long-term loyalty. The app allows him to see a consumer's current balance and rate, making it easier to provide personalized advice when the market finally hits the right threshold.
Mark Witte and Alice Lund are planning targeted neighborhood outreach programs for 2025. By focusing on 'neighborhood heroes' like teachers, hospital workers, and fire departments, they aim to build brand authority through education. These groups often benefit from specialized programs, and providing a free financial tool like 'Ready, Set, Home' or 'Manifest With Us' serves as a low-pressure way to start a professional relationship. The goal is to lead with value first, ensuring that when these heroes are ready to buy, the loan officer is already their trusted advisor.
Alice Lund emphasized that the key for the upcoming year is to not let the captured leads go to waste. With hundreds and eventually thousands of users in their 'lockers,' the focus will be on maintaining the community and responding to the 'Christmas morning' alerts when credit scores improve. By staying consistent with the basics of education and utilizing the technology to its full capacity, these loan officers plan to remain calm and prepared for whenever the next market shift occurs, keeping their clients on a steady path to homeownership.
Recruiting and Scaling Through Technology
Abdel Khawatmi highlighted how prmg uses its technology stack as a primary tool for recruiting top-tier loan officers. By showing prospective recruits how tools like 'Path Home,' MBS Highway, and Sales Boomerang can increase their production, the company attracts professionals who want to move beyond stagnant, traditional methods. Khawatmi noted that loan officers who use multiple integrated technologies can see growth of 500% to 600% in their business metrics.
The recruitment strategy relies on demonstrating the actual implementation of these tools rather than just providing a 'tech stack' in name only. Performance marketing managers work with loan officers to ensure they know how to push consumers into the branded funnels. This includes using digital business cards and social media to drive downloads. By providing a clear path for growth, the company seizes market share from lenders who are slower to adopt digital engagement strategies, positioning their team as the most tech-forward in their local markets.
Finally, the panel concluded that being a 'giver first' is the ultimate strategy for scaling a mortgage business. Whether it is providing a free living trust through the app or offering a comprehensive homebuyer workshop, the most successful loan officers are those who lead with education. By using a branded app to provide ongoing, experiential education, professionals can build a brand that pays dividends for years. The technology serves as the foundation for a relationship-driven business model that prioritizes the consumer's long-term financial health over a single transaction.
Frequently asked questions
What is the mortgage readiness feature mentioned by Brian Vieaux?
The mortgage readiness feature, often called the home ownership snapshot, is a snapshot widget within the app that helps consumers understand their approvability. Brian Vieaux noted that users often run this simulator four to six times in the first few days of creating an account to find their optimal approvability scenario.
How do these apps help loan officers save on credit costs?
The apps utilize soft credit pulls and ongoing monitoring, allowing loan officers to track a client's credit progress without incurring the high costs of multiple hard credit pulls. This also prevents the generation of trigger leads, which typically occur when a hard credit pull is executed, saving the professional from trigger leads and competitor interference.
What is the 'digital business card' coming to the platform?
It is a mobile-stored card that loan officers can use to quickly invite consumers to download their branded app. It includes the app's value proposition, pertinent information on the loan officer, and a unique link tied to the specific professional to ensure proper lead routing.
Can real estate agents be co-branded on these apps?
Yes. Loan officers can create unique URLs for an infinite number of realtor partners. When a consumer signs up via an agent's link, the agent is visible on the enrollment landing page, allowing the realtor and loan officer to 'lock arms' in the education process.
What is 'Keysteps' in the FinLocker ecosystem?
Keysteps is a version of the FinLocker product specifically created for individual loan officers who work for companies that do not yet have an enterprise-wide agreement. It allows them to utilize the platform's tools independently to engage their own database and sphere.
How does the app integration with Total Expert work?
When a consumer creates an account on the app, the integration automatically creates a new lead record in the loan officer’s Total Expert CRM. The integration also uses the CRM's journey features to trigger specific communications based on events like credit score changes recorded in the app.
Why does Minh Nguyen emphasize value checks for homes?
Minh Nguyen uses the 'fear factor' of overpaying to drive downloads. Minh Nguyen uses the 'fear factor' of overpaying to drive downloads. The value check feature tells the consumer if a house is overpriced, providing immediate value and a reason to engage with the 'Wham Wallet' before they write an offer.
How are these apps used for post-closing engagement?
Apps like PRMG's 'Path Home' are designed to stay top-of-mind by tracking property equity and providing market updates after a loan has closed. This ensures the loan officer remains the primary financial resource for the consumer for future refinances or move-up home purchases.
To talk with PRMG Got Mortgages, call 973-536-0276, visit GotMortgages.com, contact the team or build your mortgage plan.
Explore more Got Mortgages Insights and Abdel Khawatmi’s profile. Explore more conversations at the Got Mortgages Podcast website.
Author: Abdel Khawatmi with PRMG Got Mortgages | 973-536-0276
This article is general mortgage information only. It is not a commitment to lend, a rate quote, or legal or tax advice. Loan approval, terms and pricing depend on a full application, credit review and property details, and market conditions change. Talk with a licensed loan officer and your own legal or tax professional about your situation. NMLS #1712023 | PRMG NMLS #75243.